Homeowners Insurance in Carmel, IN That Fits Your Home.
From established Carmel neighborhoods and new construction in Westfield to homes on the Georgia coast, we compare homeowners insurance across 14+ carriers and explain what each policy does and doesn't cover.
Tell us what you have
Send the form, call, or text. If you have your current policy handy, even better.
We shop 14+ carriers
Same coverage on every quote, so the price differences you see are real.
You pick, we handle the switch
We set up the new policy, notify your lender if needed, and stay your contact after.
More Than a Price
on a Declarations Page.
A homeowners policy is several coverages in one. Here's what we review with you.
Dwelling & Other Structures
Pays to repair or rebuild your home and covers detached structures like a garage, shed, or fence, up to your policy limits.
- ✓ Insure to rebuild cost, not purchase price
- ✓ Replacement cost vs. actual cash value matters
- ✓ We check how each carrier estimates rebuild cost
Personal Property & Loss of Use
Covers furniture, clothing, electronics, and more. If a covered loss makes your home unlivable, loss of use helps with temporary housing and extra living costs.
- ✓ Replacement cost on contents is an option on many policies
- ✓ High-value items may need to be scheduled separately
- ✓ Limits and options vary by carrier
Liability & Medical Payments
Helps if someone is hurt on your property or you're held responsible for damage to someone else's, including legal defense costs.
- ✓ Higher liability limits are often available
- ✓ Pairs with an umbrella for more protection
- ✓ Dog and pool questions affect eligibility at some carriers
What Standard Policies Leave Out
Standard homeowners policies typically exclude flood and earthquake. Water backup is often an add-on, and some carriers use separate wind/hail deductibles or roof-age schedules.
- ✓ Flood is covered separately (NFIP or private)
- ✓ Ask about water backup and sump overflow
- ✓ Coastal Georgia homes need a closer wind and flood review
A few things worth knowing.
Homeowners insurance has more fine print than most policies. These are the questions that matter most.
Insure the cost to rebuild. Your home's market value and its rebuild cost are different numbers. Rebuild cost is what matters for the dwelling limit.
Roof age and condition matter. Carriers differ on how they treat older roofs, in both eligibility and how claims are paid, so it's worth comparing.
Timing at closing. Your lender needs proof of coverage before you close. We recommend starting as soon as you're under contract.
Discounts vary by carrier. Bundling, claims history, and protective devices can all affect price, but each carrier handles them differently.
Homeowners Insurance, Answered
Ready to compare homeowners insurance options?
Tell us what you're looking for and we'll shop 14+ carriers for you. No obligation. Rated 5.0 from 30 Google reviews.
"Spencer did a great job putting together a home quote that was below my previous policy. Communication was easy and he got the policy set up with my mortgage lender."
"He took the time to give me estimates to cover our home, including a comparison to our current policy."
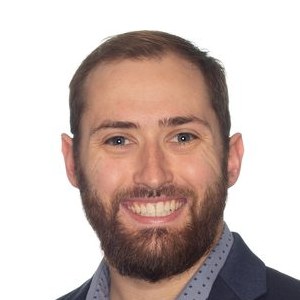
You'll hear from Spencer personally. A local agent in Carmel, not a call center.
Got it. Thank you.
Spencer will call or text you within one business day. Need an answer sooner? Call or text 317-991-1101.