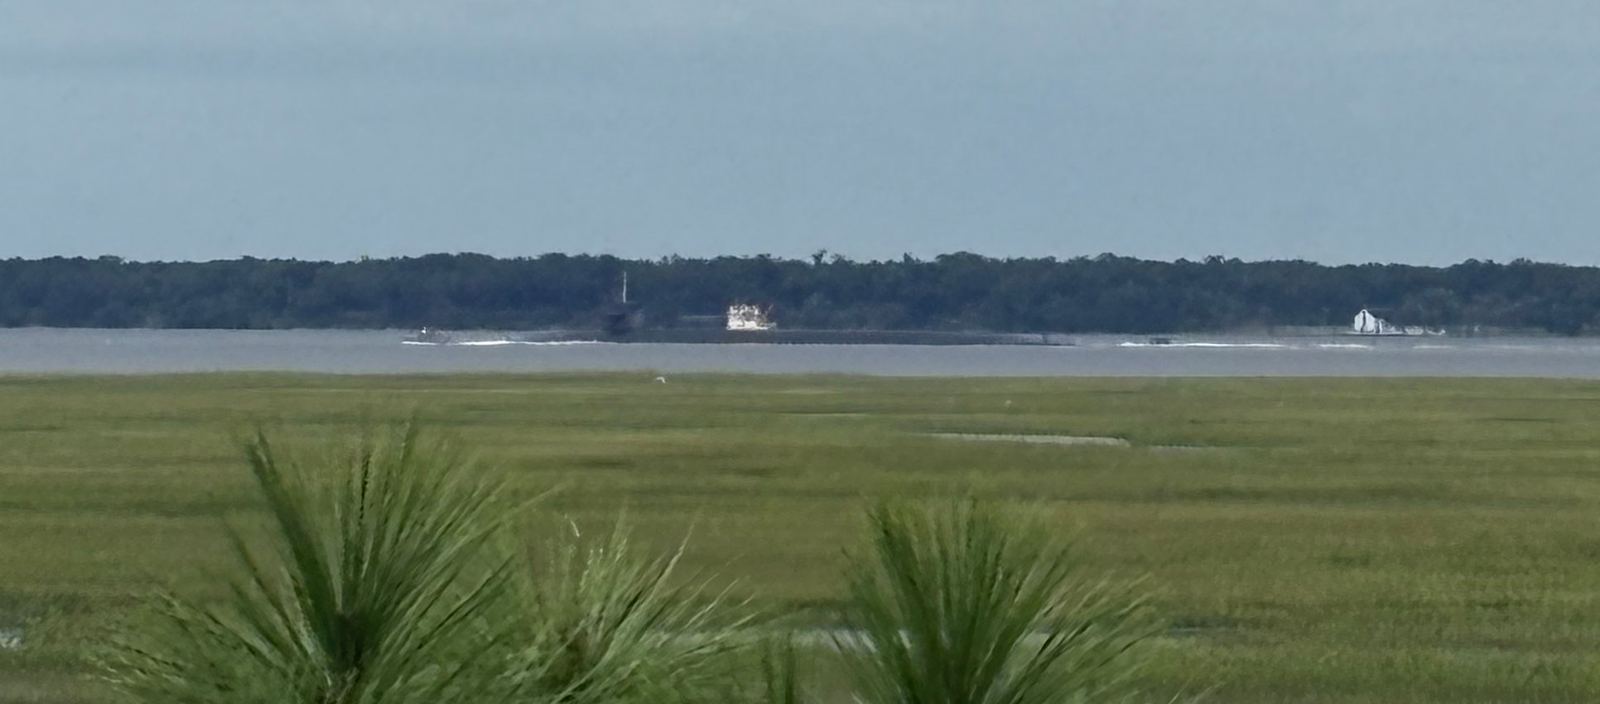
Living on the Georgia coast means thinking about your home insurance differently than most homeowners. We compare NFIP and private flood insurance side by side, and work with specialty home carriers built for coastal risk — so you get the right coverage, not just the required minimum.
Send the form, call, or text. If you have your current policy handy, even better.
Same coverage on every quote, so the price differences you see are real.
We set up the new policy, notify your lender if needed, and stay your contact after.
Standard homeowners insurance doesn't cover flood damage — it's always a separate policy. For coastal Georgia homes, that policy usually comes from one of two places.
The National Flood Insurance Program is administered through FEMA and offered nationwide through participating carriers. It's the most familiar option, and it's often required by mortgage lenders for homes in a high-risk flood zone (a Special Flood Hazard Area).
Written by private carriers outside the NFIP — including specialty and wholesale markets we work with directly. Private flood can be a strong option when you want higher limits or broader protection than the NFIP provides.
Flood insurance isn't one-size-fits-all, and the right answer depends on your specific home and flood zone. As an independent agent, we're not limited to selling you just NFIP or just one private carrier — and flood is only part of insuring a coastal home.
We compare NFIP and private quotes side by side — so you can see the coverage and the price of each before deciding.
We check your flood zone as part of putting together your quote, so you know whether flood coverage is required or optional for your property.
We have access to specialty and wholesale flood markets — carriers most homeowners can't reach directly — for coastal properties that need more than a standard policy offers.
We also work with specialty home insurance carriers for the rest of your coastal property — not just flood. Standard homeowners carriers can be hesitant to write policies close to the coast, so we place the underlying dwelling policy with carriers built for coastal risk when a standard carrier won't.
We handle the mortgage escrow and lender requirements so your flood coverage lines up with what your lender actually needs.
In Camden County? See our dedicated page for St. Marys, Kingsland & Camden County insurance, including coverage for Kings Bay Naval Submarine Base families.
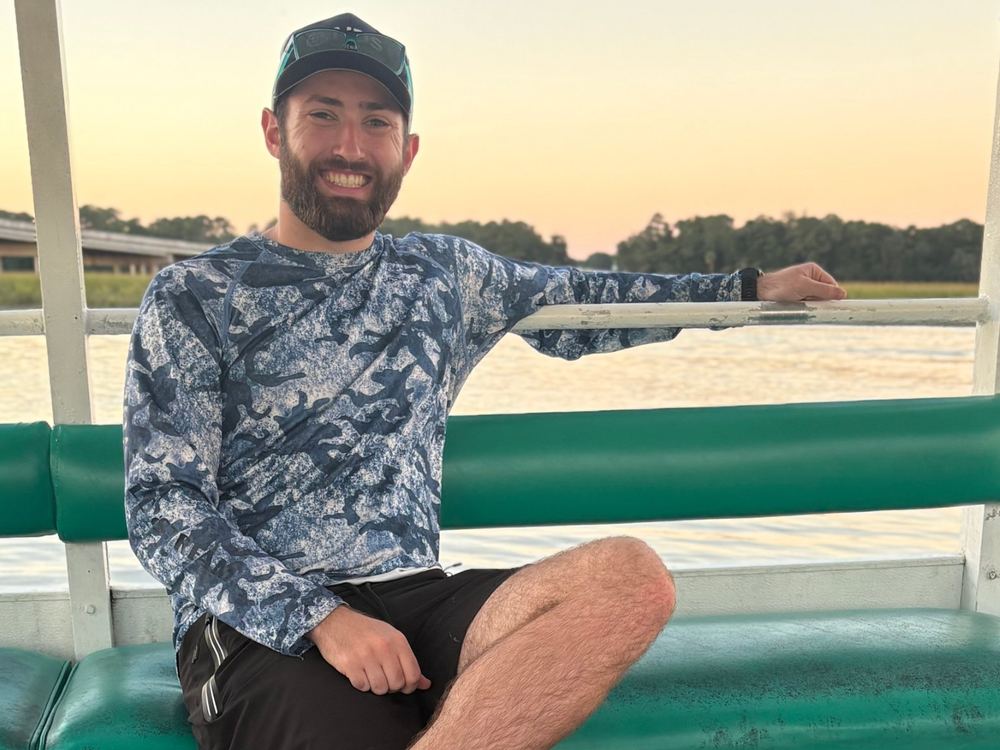
Spencer's family calls the Georgia coast home, and he's there often. Tides, marsh, and storm season aren't abstract to us, which helps when we're matching a coastal home with the right carrier.
Tell us a bit about your coastal Georgia property and we'll compare NFIP and private options for you — no obligation.
"Spencer and his team were very efficient and thorough on evaluating and replacing policies for my primary residence, personal articles, autos and rental properties when costs with my prior agency grew excessive."
"Spencer did a great job putting together a home quote that was below my previous policy. Communication was easy and he got the policy set up with my mortgage lender."
You'll hear from Spencer personally. A local agent in Carmel, not a call center.
Spencer will call or text you within one business day. Need an answer sooner? Call or text 317-991-1101.