Condo & Townhome Insurance in Carmel and Hamilton County.
A condo policy fills the gap between what your association's master policy covers and what you own. From our Carmel office we read the master policy requirements and compare HO-6 coverage across 14+ carriers.
Tell us what you have
Send the form, call, or text. If you have your current policy handy, even better.
We shop 14+ carriers
Same coverage on every quote, so the price differences you see are real.
You pick, we handle the switch
We set up the new policy, notify your lender if needed, and stay your contact after.
Covering Your Side
of the Walls.
Associations insure the building. These are the parts that are usually yours.
Interior & Improvements
Depending on the association's master policy, you may be responsible for drywall, flooring, cabinets, fixtures, and any upgrades inside your unit.
- ✓ Master policies range from bare walls to all-in
- ✓ Your dwelling limit should match your share
- ✓ Upgrades you made are usually yours to insure
Personal Property
Covers furniture, clothing, electronics, and other belongings against covered losses like fire and theft.
- ✓ Ask about replacement cost on contents
- ✓ Jewelry and collectibles often have sub-limits
- ✓ A home inventory makes claims easier
Personal Liability
Protects you if someone is hurt in your unit or you cause damage to another unit, such as a leak that runs into the unit below.
- ✓ Medical payments coverage for guests
- ✓ Liability limits you can raise
- ✓ Pairs with an umbrella policy
Loss Assessment
If the association charges owners for a covered loss or for the master policy's deductible, loss assessment coverage can help pay your share.
- ✓ Default limits are often low
- ✓ Higher limits are usually inexpensive
- ✓ Check your HOA's master deductible
Start with the master policy.
The right condo policy depends on what your association already insures.
We read the HOA requirements. Send us the master policy summary or governing documents and we'll match your coverage to what the association leaves to you.
Townhomes aren't always condos. If you own the structure and the land under it, a homeowners policy may be the right form. It depends on how the property is deeded and what the HOA insures.
Lenders want proof. Your mortgage company will usually require an HO-6 policy. We send the evidence of insurance to your lender.
Bundle with auto. Many carriers discount condo and auto together, and we check each carrier's bundle.
Condo Insurance, Answered
Ready to compare condo insurance options?
Tell us what you're looking for and we'll shop 14+ carriers for you. No obligation. Rated 5.0 from 30 Google reviews.
"Spencer did a great job putting together a home quote that was below my previous policy. Communication was easy and he got the policy set up with my mortgage lender."
"He took the time to give me estimates to cover our home, including a comparison to our current policy."
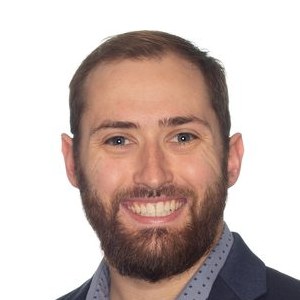
You'll hear from Spencer personally. A local agent in Carmel, not a call center.
Got it. Thank you.
Spencer will call or text you within one business day. Need an answer sooner? Call or text 317-991-1101.